
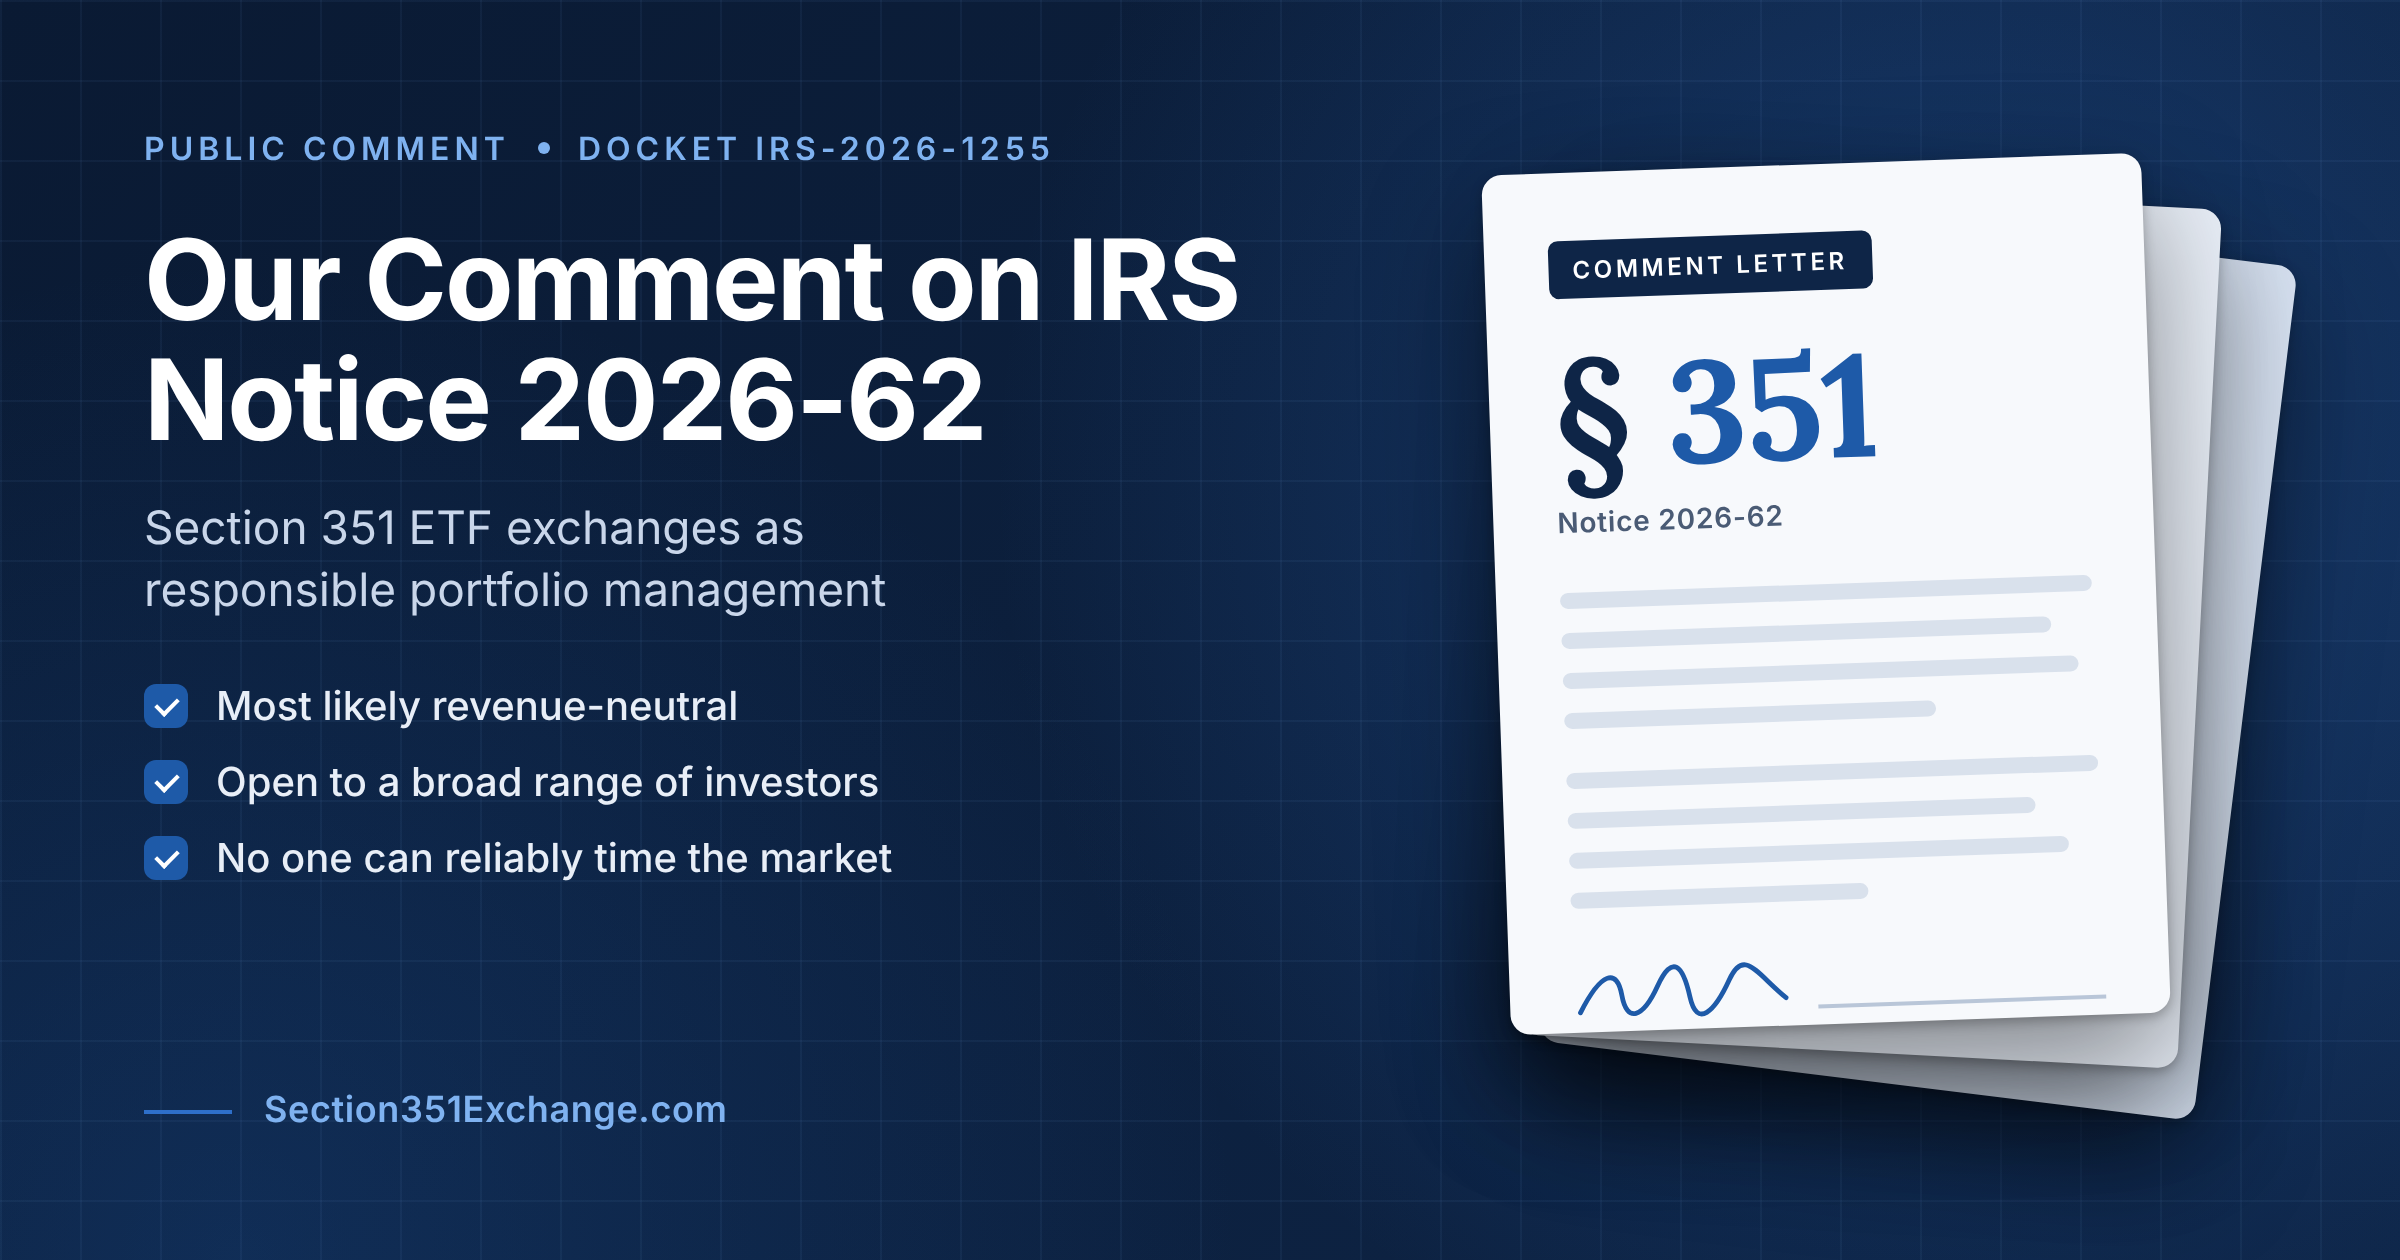
On September 28, 2026, the Treasury Department and the IRS released Notice 2026-62 and Rev. Rul. 2026-20. The Notice asks for public comment on certain Section 351 ETF transactions and other fund strategies. ExchangiFi submitted a comment letter, and it is now posted on Regulations.gov.
[View all comments in Docket IRS-2026-1255]
What does Notice 2026-62 say about Section 351 ETFs?
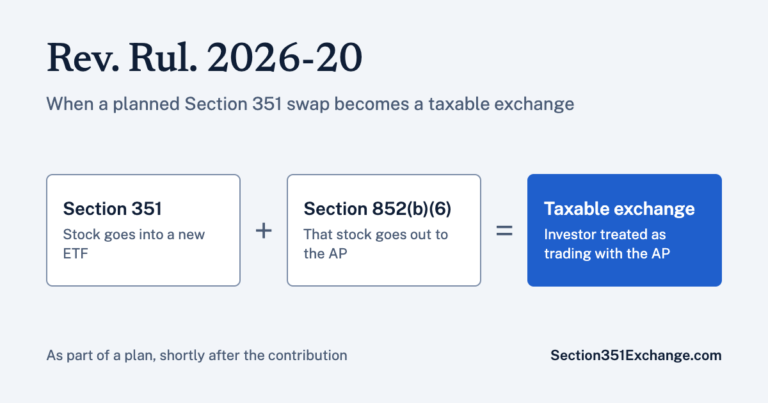
The Notice describes a “Section 351 conversion transaction.” Investors contribute securities to a new ETF, and the fund then redeems those securities out to an authorized participant shortly after launch. Rev. Rul. 2026-20 treats that pattern as a taxable exchange. The Notice states that it does not address seeding a new ETF with securities that fit the fund’s strategy and that the fund intends to keep.
What did ExchangiFi say in its comment letter?
In our experience, Section 351 ETF launches are generally seeding transactions of the kind the Notice does not address. Our letter makes three main points.
- Most likely revenue-neutral. For most investors, the realistic alternative is holding their stocks indefinitely, not selling. A Section 351 exchange defers tax. It does not eliminate it.
- Not just for the wealthy. The wealthiest investors have many tax deferral tools, most limited to accredited investors or qualified purchasers. A Section 351 exchange into a registered ETF is open to a broad range of investors.
- Responsible portfolio management. Moving a fragmented portfolio into a professionally managed ETF is sound practice. No one can reliably time the market or predict which strategy will win.
[Read ExchangiFi’s comment letter]
What did ExchangiFi recommend?
We recommended that the Treasury Department and the IRS rely on targeted information reporting, similar to the reporting used for like-kind exchanges, rather than identifying Section 351 ETF seeding as a listed transaction or transaction of interest.
When is the comment deadline?
The comment period closes October 28, 2026. Anyone can submit a comment on Regulations.gov by searching for Docket IRS-2026-1255.
ExchangiFi LLC provides technology and is not a registered investment adviser or broker-dealer. This post is for informational purposes only and is not tax, legal or investment advice. Section 351 treatment depends on the facts and circumstances of each portfolio. Consult your own tax and legal counsel before acting.
https://section351exchange.com/wp-content/uploads/2026/10/Bucklin-Comment-Letter-Notice-2026-62.pdf