
What Rev. Rul. 2026-20 Means for Section 351 ETF Exchanges
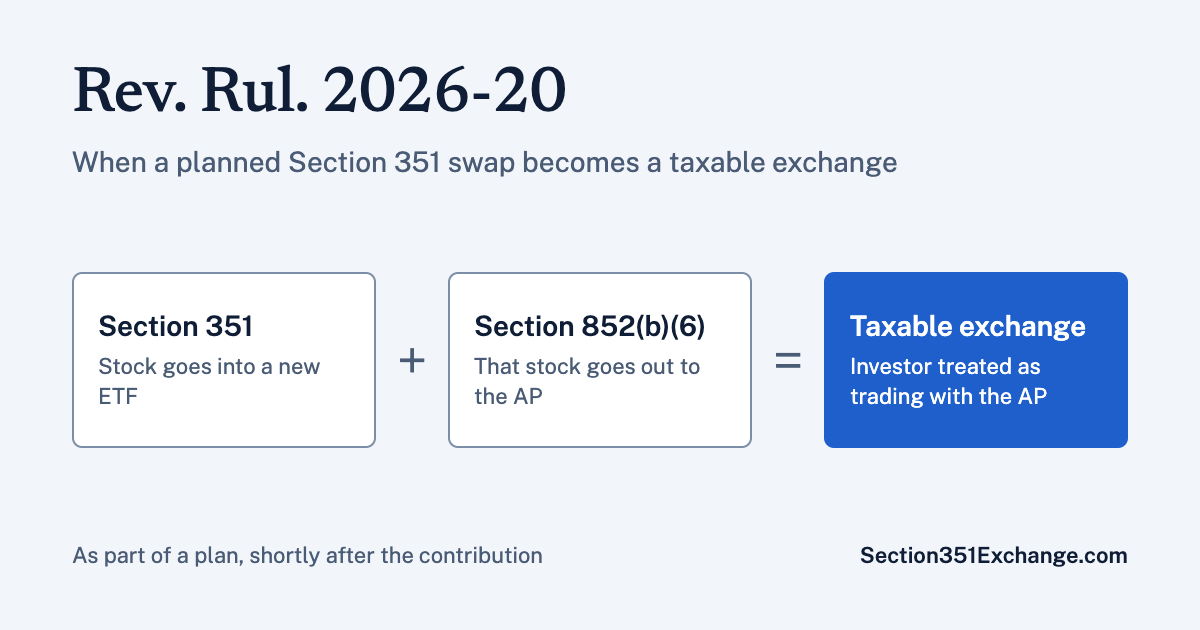
On September 28, 2026, the IRS released Rev. Rul. 2026-20 alongside Notice 2026-62. The ruling addresses one specific Section 351 ETF pattern. It does not target Section 351 seeding broadly. Here is a full summary of the ruling. The pattern is a planned swap. An investor contributes stock to a new ETF. Shortly after, the … Read more