Section 351 Exchange

What Rev. Rul. 2026-20 Means for Section 351 ETF Exchanges
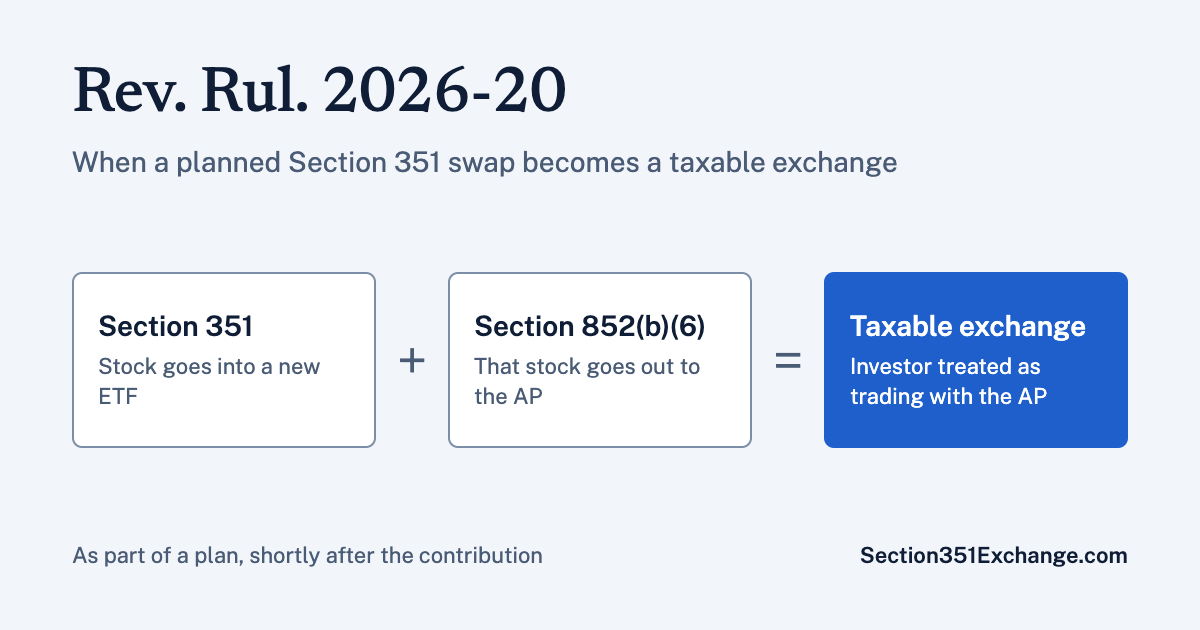
Graphic showing a Section 351 contribution plus a Section 852(b)(6) redemption, done as part of a plan, treated as a taxable exchange under Rev. Rul. 2026-20

On September 28, 2026, the IRS released Rev. Rul. 2026-20 alongside Notice 2026-62. The ruling addresses one specific Section 351 ETF pattern. It does not target Section 351 seeding broadly. Here is a full summary of the ruling. The pattern is a planned swap. An investor contributes stock to a new ETF. Shortly after, the … Read more
Treasury Scrutiny of Tax-Aware ETF Strategies and What It Means for Section 351 Exchanges

Treasury and IRS Put Certain “Tax-Aware” Financial Product Strategies on Notice

Treasury and the IRS have put certain tax-aware financial product strategies on notice. A recent Perkins Coie panel moderated by Mohsen Ghazi, with partners Sharon Kim and Vivek Chandrasekhar, walked through what that scrutiny actually covers. The short version is that ordinary ETF activity and ordinary tax loss harvesting are not the target. Stacked structures … Read more

The Tax Court’s Blueprint: What SIH Partners Means for Section 351 ETF Seeding

What SIH Partners Means for Section 351 ETF Seeding

In the high-stakes world of corporate tax strategy, practitioners often assume that if you follow the literal math of a regulation, you’re safe. The recent Tax Court decision in SIH Partners v. Commissioner proves that while the math matters, the underlying intent matters just as much. The case involved a sophisticated dividend arbitrage transaction. The … Read more

Where Treasury Drew the Line on Tax-Aware ETFs

treasury-tax-aware-etfs-cover

Key takeaways from the Wall Street Tax Association panel with Treasury and IRS officials, July 2026. Treasury and the IRS spent Tuesday morning walking through the tax-aware product strategies they are watching. It was a Wall Street Tax Association seminar with Kevin Salinger and Erika Nijenhuis from Treasury’s Office of Tax Policy, alongside partners from … Read more

The Guardrails That Decide Who Gets to Access the $5.0 Trillion Market

Guardrails That Decide Who Gets to Access the $5.0 Trillion Market

ExchangiFi’s new white paper sizes the Section 351 conversion opportunity at an estimated $5.0 trillion. The number gets the attention. The compliance architecture decides who can actually use it. Section 351’s nonrecognition treatment is conditional, and the conditions are unforgiving. The central obstacle is Section 351(e). To stop investors from pooling concentrated stock into instant … Read more

Section 351 ETF Exchanges: The Complete Legal and Tax Framework

legal framework of Section 351 ETF exchanges

Here is a comprehensive list of the legal authorities, statutes, regulations, rulings, cases, and doctrines that support and govern the legality of a Section 351 exchange of securities into an ETF: Internal Revenue Code (IRC) Statutes The foundation of the tax-deferred conversion relies on specific sections of the IRC governing corporate formations and investment companies: … Read more

Section 351 Exchange Mistakes to Avoid

section 351 exchange eligible assets

Most failed Section 351 exchanges do not fail because the strategy is wrong. They fail because of preventable errors that surface late in the process or, worse, after the transaction has closed. The tax authority is well established. The mechanics are well understood. The errors are usually in the execution. This guide walks through the … Read more