Section 351 Exchange

What Rev. Rul. 2026-20 Means for Section 351 ETF Exchanges
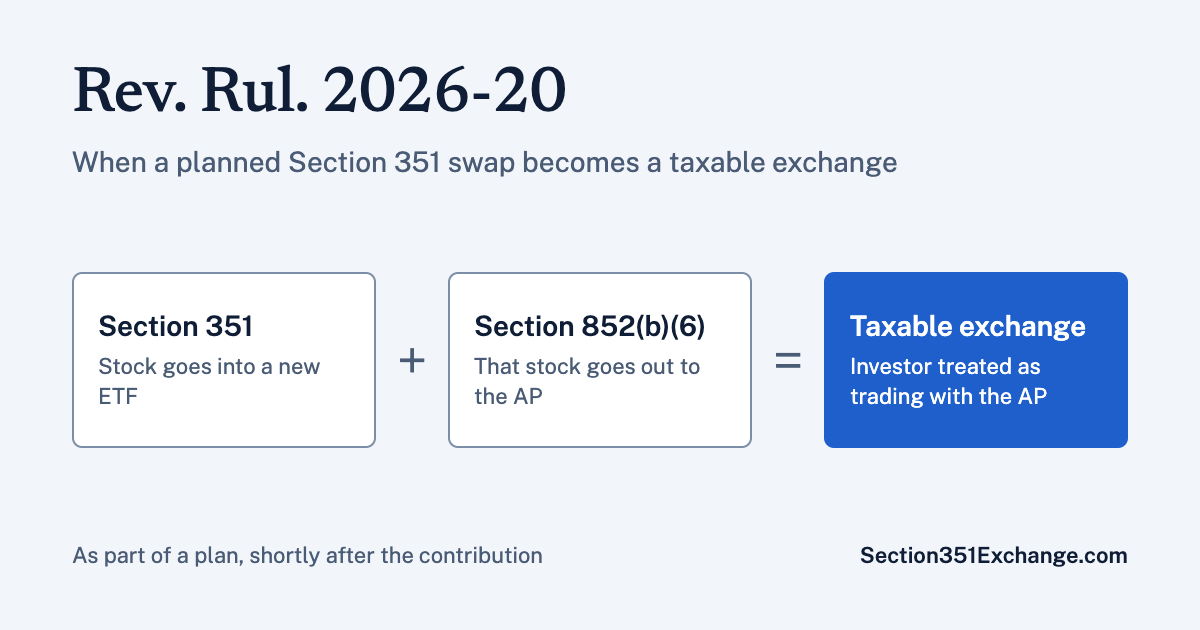
Graphic showing a Section 351 contribution plus a Section 852(b)(6) redemption, done as part of a plan, treated as a taxable exchange under Rev. Rul. 2026-20

On September 28, 2026, the IRS released Rev. Rul. 2026-20 alongside Notice 2026-62. The ruling addresses one specific Section 351 ETF pattern. It does not target Section 351 seeding broadly. Here is a full summary of the ruling. The pattern is a planned swap. An investor contributes stock to a new ETF. Shortly after, the … Read more
The Guardrails That Decide Who Gets to Access the $5.0 Trillion Market

Guardrails That Decide Who Gets to Access the $5.0 Trillion Market

ExchangiFi’s new white paper sizes the Section 351 conversion opportunity at an estimated $5.0 trillion. The number gets the attention. The compliance architecture decides who can actually use it. Section 351’s nonrecognition treatment is conditional, and the conditions are unforgiving. The central obstacle is Section 351(e). To stop investors from pooling concentrated stock into instant … Read more